

Damien Soitout
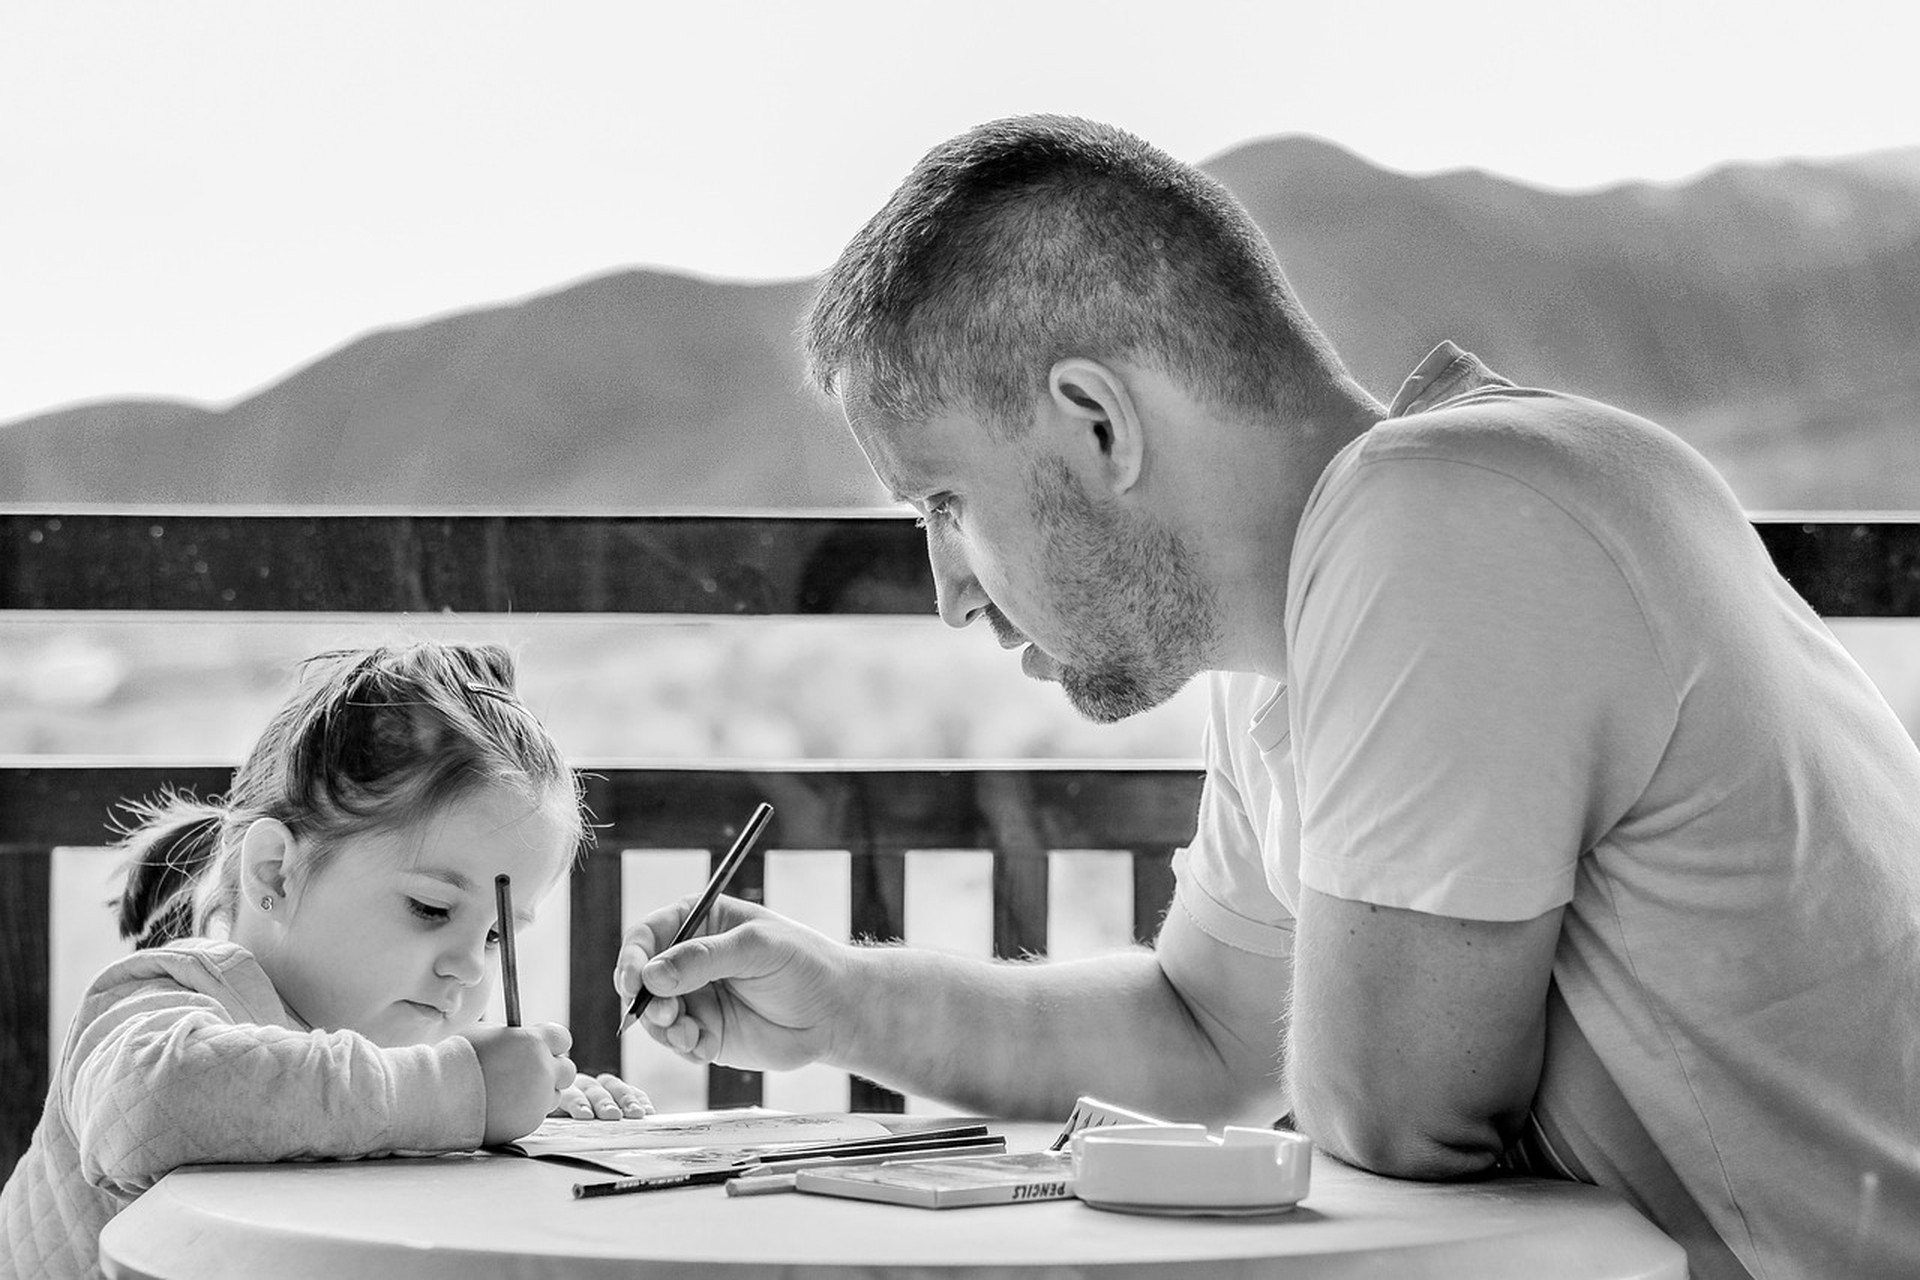
A household money conversation works when figures come from paper, questions are allowed, and the talk ends before it becomes a briefing.
The pencils are out. A money talk can stay at that scale.
Family money talks fail when they turn into lectures. I have given the lecture. I have also watched it. An adult opens a subject that frightens them, hears their own voice become a class, and is surprised when the other adult goes quiet or the young person asks to leave. The quiet is not ignorance. It is the reasonable response to being briefed. A briefing has a speaker and an audience. A home is a poor classroom, because the people in it have to go on living with the speaker after the lesson ends. On 22 August 2023 the talk I want is one another adult can stay in, and one a young person can stay in. The pencils in the picture are the right scale. You can draw a simple picture of the month. You do not need a podium.
The talk also fails when the figures are invented for effect. A round number pulled from the air teaches the listener that money is a story adults tell when they are anxious. A number from a statement teaches that money is a record. Asking the right question matters more, in this room, than delivering the right speech. The right question can be answered from paper. The speech can be delivered from fear. Fear is allowed. It is a bad teacher.
Set the talk up so it cannot become a class. Two conditions are enough. First, everyone who is in the conversation can ask a question, including a question the adult would rather postpone. Second, every figure that enters the room comes from a document you can put on the table, or it does not enter. A guess announced with confidence is still a guess. Citizens Advice, on how to work out your budget, gives the same standard for a written budget. The advice is written for England, with sister pages for Scotland, Wales, and Northern Ireland. It says the planner is most useful when the figures are accurate, that rough figures are only for a general picture, and that you should find the recent statements, payslips, card bills, and the receipts for what you pay in cash. It tells you to include what you spend on a partner or a family, not only the bills with your name on them. That inclusion is already a better money talk than most speeches. The spending that has no line is the spending people fight about. Put it on a line, from paper, and the fight has less mythology in it.
The same page points to a free budget planner. Use a tool if it helps you see the month. Do not use the tool as a performance. A household can sit with one month, the way managing a monthly budget already asks, and mark three kinds of lines: what must be paid, what is chosen, and what is a leak nobody decided. How to read a month of spending is the discipline of using the month you lived, not a fantasy total. Price a life change before you invent the budget is the same allergy to invented numbers, applied to a bigger move. A talk at the kitchen table is smaller. It still dies if the first number is a fiction.
Whether money buys happiness can wait until the lines are real. Happiness is a poor opener. It invites a speech about values and postpones the rent. Values matter after the month is visible. People can disagree about a want. They cannot usefully disagree about a bill they have not looked at. Look first. Then ask what the month is for. The question “what do we want this money to do” is a conversation. The sentence “let me explain how money works” is a lecture. I have heard the second sentence from people who love their families. Love was not the problem. The form was the problem. Change the form and the love has a place to sit.
UNICEF's parenting pages on child development start from a plain claim. A child's environment and experiences shape how they grow, in health and in mind, from pregnancy onward. The pages are full of milestones, play, language, and the move toward school. Money is part of that environment whether or not you schedule a lesson. Children hear the tone long before they understand an interest rate. A house that only mentions money in anger teaches that money is danger. A house that only mentions money in boasts teaches that money is theatre. A house that sometimes puts a statement on the table, and lets a question be asked, teaches that money is a tool adults handle in the open.
Teaching children the value of money is the longer piece, and raising responsible children is the wider one. Neither one requires a seminar. A young person can learn three concrete things in a short talk. What the household pays so that the lights and the food continue. What money they handle themselves, and what it is for. What a want costs in time, not in a speech about gratitude. Time is the translation that works. If a sum is also a pile of hours, a child can feel the trade without being frightened by the whole budget. You do not owe them every number. You owe them a true number at the scale of their life: the price of the thing they want, the money they have, and the difference. Children and screens belongs in the same hour only as a boundary. A money talk with a phone in every hand becomes a lecture plus a distraction. One rule for the phone at the table keeps the pencils in use.
Age changes the concrete thing, not the tone. A small child can match a coin to a piece of fruit. An older child can see a week of their own spending written down by them, not prosecuted by you. A teenager can sit in on one real bill and ask what would change if it rose. You still do not perform the entire fear of the household in front of them. Adults have a separate conversation for the fear, with the documents, when the children are not the audience. Putting a child in the audience of adult panic is not financial education. It is a transfer of anxiety. UNICEF's point about environment cuts both ways. The environment includes the calm as well as the fact.
A lecture recites rules from memory. A conversation opens the rule and reads it. Where the money sits is the risk is a good thing to look up rather than to perform. If the household's cash is a deposit, the Federal Deposit Insurance Corporation's page on understanding deposit insurance says what that insurance is: protection of deposit accounts at an insured bank if the bank fails, at least 250,000 dollars per depositor, per ownership category, at each insured bank. It also says what is not a deposit. Stocks, mutual funds, and the contents of a safe deposit box are not covered just because a bank sold them or stored them. You can read that paragraph with another adult, or with a teenager, and ask one question. Which of our lines is a deposit, and which line only feels like one? The question does not require you to announce a balance to the table. The type of seat is enough. A higher price of money is the other public fact you look up on the day, at the central bank, rather than quoting a rate you remember. The figure belongs to the day you read it. The talk belongs to the household. Do not weld them into a forecast.
If the talk is about debt, use the statements, not a speech about character. Character lectures feel powerful and teach shame. Shame hides the next statement. A statement on the table, with a question about which line can be paid and which line is the one you will stop growing, is a plan. Citizens Advice is explicit that if court papers, eviction, or bailiffs are already in the picture, you talk to an adviser immediately rather than to a webpage. That is the right size of alarm. A family conversation is for the month you can still shape. A legal deadline is a different room, with a person whose job is that deadline. Do not use the kitchen table as a substitute for advice you need from someone qualified, and do not use the fear of that advice as a reason to lecture the people you live with.
Twenty minutes is a full talk. End with one decision or one question you will answer next time from paper. A decision might be which subscription stops, or who asks the insurer for the document you cannot find, or that a want waits until a date you both heard. A question might be what the food line actually was last month, to be answered when the receipts are in a pile. Write the decision where you will see it. Then stop talking. The surplus speech is how a conversation becomes a lecture in the last five minutes, when the adult feels the point has not landed and adds a moral. The moral is the part people remember with irritation. The decision is the part that changes the month.
A money talk at home that is not a lecture has paper, questions, a public rule when you need one, and an end. Another adult can stay because they were not seated as a pupil. A young person can stay because the scale matched their life and the tone matched a kitchen. Put a ceiling on what you give, when the season of gifts arrives, is the same instinct later in the year: a limit chosen before the mood spends the money. The talk is where a household learns to choose limits out loud. Choose one this week. Leave the podium in the other room.


